Compare businesses, not just doors
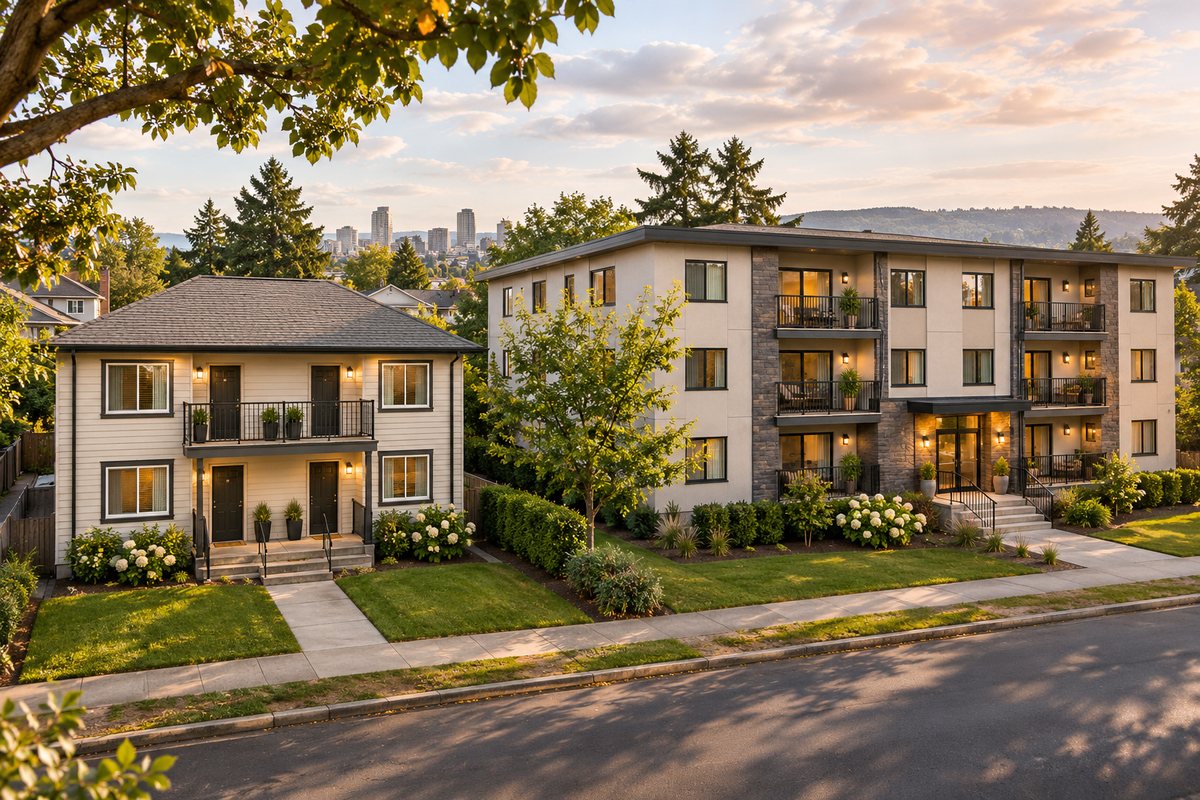
This hypothetical comparison places a fourplex beside a twelve-unit apartment building. Both can be worthwhile investments, but they require different capital, financing and operating capacity. The purpose is to show how to compare them consistently rather than declare that a larger property is automatically better.
Assume the fourplex costs $700,000 and has $6,000 monthly scheduled rent, or $72,000 annually. After illustrative vacancy and operating expenses, NOI is $42,000. The twelve-unit building costs $1,800,000, has $216,000 annual scheduled rent and $120,000 NOI. These are constructed teaching inputs, not market examples.
Compare operating economics first
The fourplex's NOI-to-price ratio is six percent. The apartment building's is about 6.67 percent. That difference does not capture condition, location, capital needs or the stability of collections. Review those factors before treating the larger percentage as a stronger investment.
One vacant unit represents 25 percent of the fourplex's units and about 8.3 percent of the apartment building's units. The actual rent loss depends on the vacant unit's rent. The apartment has more diversified unit-level collections, but it also has more systems, resident relationships and administrative work. Scale creates both efficiencies and obligations.
Apply each financing method correctly
Suppose an illustrative fourplex loan is $490,000 at eight percent over 30 years. Annual principal and interest are about $43,146. Against $42,000 NOI, the simple economic result is slightly negative before separate capital funding. A residential DSCR lender might use a different rent-to-PITIA qualification method; that does not change the investor's full operating result.
For the apartment, suppose a $1,170,000 loan carries a hypothetical annual mortgage constant of eight percent. Annual debt service is $93,600 and NOI-based coverage is approximately 1.28. Annual cash after debt is $26,400 before separately identified capital funding and other non-operating items. Actual loan terms and lender adjustments could change the result.
Include the owner's capacity
The fourplex down payment is $210,000 under the stated loan assumption; the apartment contribution is $630,000 before closing costs, reserves and initial work. Compare cash-on-cash only after the full capital contribution and distributable cash are defined. Larger dollar cash flow can still require a much larger investment and more operating support.
The final decision should include inspection-based capital needs, available liquidity, management quality and the investor's experience. The apartment may fit an investor prepared for commercial underwriting and scaled operations. The fourplex may offer a more manageable learning environment, but its purchase price and debt still need to work. The best next door is the property whose verified business plan fits both the numbers and the owner who must execute it.
Add a common downside case
Reduce scheduled collections by five percent of potential rent for each property while holding expenses constant for this simplified exercise. The fourplex loses $3,600 annually and the apartment loses $10,800. The actual expense response could differ, so this is only one sensitivity.
Under the stated debt assumptions, the fourplex's already thin economic result becomes more negative. The apartment's cash after debt falls from $26,400 to $15,600 before capital funding. Its coverage declines from about 1.28 to about 1.17 if NOI falls to $109,200. This shows why the larger property still needs reserves despite more diversified unit income.
Compare the cash needed to absorb that period with each investor's available resources and planned capital work. The choice is not simply four versus twelve doors. It is the combination of verified income, debt, capital needs and management capacity that remains workable when operations differ from the base case. That is the comparison worth carrying into a real acquisition discussion.
Reference desk: compare the full equity commitment
The down payment is only the opening contribution. Add transaction costs, reserve deposits, immediate repairs and operating setup to define total cash committed. Use the same convention for both buildings. Otherwise the larger property's return may be overstated or understated simply because the denominator is incomplete.
Review inspection-based capital needs separately from annual NOI. One property may have a recently replaced roof while the other requires substantial near-term work. Equal operating yields do not make those capital positions equal. Include a multiyear schedule and the funding needed before comparing distributions.
Management capacity also belongs in the decision. A twelve-unit property can justify more formal systems while requiring greater coordination. A fourplex may be easier to learn in detail but still demand reliable maintenance and resident administration. Price the intended service arrangement into both budgets.
Use actual lender methods rather than forcing the same qualification formula onto both categories. The investor can compare economic cash flow consistently while recognizing different underwriting approaches. Show each lender's accepted income, payment assumptions and final proceeds in a separate financing section.
Test exit and maturity at a common review date. Calculate remaining debt, potential transaction costs and the effect of a lower value or smaller refinance. Equity is sensitive to both asset performance and debt. A larger building with stronger base cash flow can still create a significant future contribution if leverage or maturity is poorly matched.
The final recommendation should explain fit: verified operations, required cash, capital schedule, management and financing. A property is suitable when the investor has the resources and process to carry out its plan. Comparing four and twelve units this way turns door count into a starting description rather than a conclusion, supporting a more informed and sustainable step into multifamily ownership.
Compare the smallest projected cash balance for both buildings after capital work and downside operations, then assess which plan your available resources and management capacity can sustain.
Sources, further reading and editorial notes
- Fannie Mae: General Property Eligibility
One-to-four-unit property eligibility and legal-use framework.
- Fannie Mae: Conventional Properties Term Sheet
Five-or-more-unit multifamily category and example third-party report requirements.
- Freddie Mac Multifamily: Get Started
Multifamily financing category beginning with five dwelling units.
- HUD: Fair Housing Rights and Obligations
General housing-provider responsibilities; local rules require separate review.
- Federal Reserve: Prudent CRE Loan Accommodations and Workouts
Valuation premises and context for income-based commercial analysis.
Prepared November 12, 2026 for the labeled 2026 edition. The sources provide background; worked examples are original, hypothetical and rounded.
Investor education, not an offer or commitment to lend. All deal examples are hypothetical and rounded. Terms, eligibility and availability vary. Obtain appropriate legal, tax, insurance and local professional advice for your circumstances. Editorial illustrations are AI-generated and do not depict listed properties.
KEEP THE COMPLETE ISSUE
Multifamily: The Next Door
All 12 articles, the editorial introduction and the investor workbook in one 29-page PDF.
Download November 2026 PDF